Quantitative Research · Machine Learning

Hedi Khannous

Polytechnic engineer · Algorithmic trading & derivatives pricing · Mathematical rigor into production-ready ML.

01 — Resume

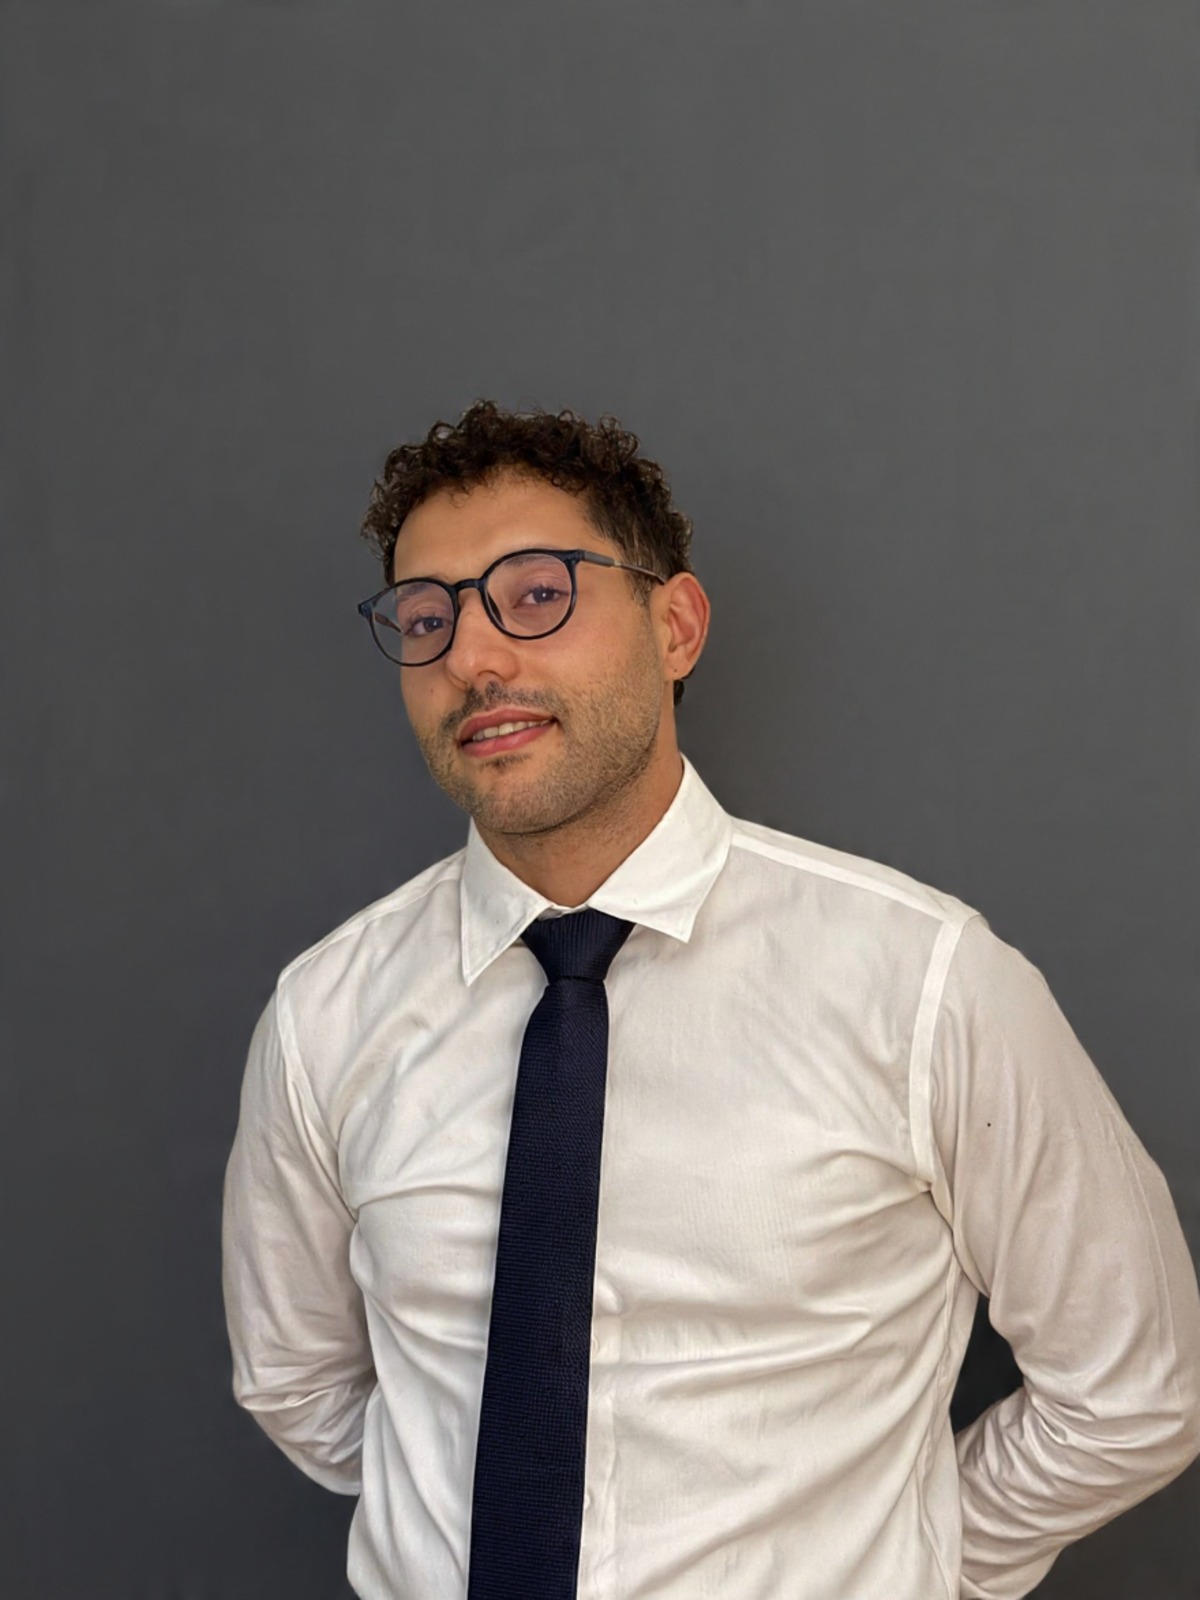
Portrait of Hedi Khannous

Research & Professional Experience

Freelance Quantitative Developer — Trading Systems & ML

Feb 2026 — Present

Independent consultant — Aethux and private clients

Remote — Rome, Italy

  • Delivered trading automation for private clients: an MQL5 Expert Advisor with modular risk controls, portfolio monitoring, and risk-aware position sizing, plus ML trade filters and live strategy monitoring on QuantConnect (Lean).
  • Delivered modular, testable Python on the Aethux Research Platform through Git-based sprints with code review, CI/CD, and client-ready handover.
  • Ran a confidential computer-vision study on public image benchmarks, comparing vision-only and image-plus-tabular models under a locked training recipe; rich clinical metadata raised multiclass balanced accuracy from 0.59 to 0.71.
Quantitative Research in ML for Algorithmic Trading & Risk

Nov 2023 — Jan 2026

  • Built and maintained a traceable, reusable ML workflow with modular pipelines, versioned datasets/features, automated validation, and performance reporting to support reproducibility and handover.
  • Evaluated 7000+ model configurations across Signature-based and engineered features (250+) over 4 commodities and 15+ years of data under realistic trading constraints; used AWS/GCP VMs to accelerate hyperparameter search during this evaluation.
  • Co-developed and validated 3 out-of-sample strategies with an industry algo-trading team, reaching about 190% cumulative net return over 4 years (after transaction costs and slippage) and a +0.1 Sharpe improvement vs benchmark in 1/4 commodities.
  • Reported model diagnostics, stress-test outcomes, and implementation trade-offs to academic and industry stakeholders to support research-to-application decisions.

Research Project: Options Pricing & Market Data Analysis in the Power Market

Feb 2023 — Jul 2023

  • Derived a closed-form valuation formula for energy Reliability Options under Merton jump-diffusion, enabling fast pricing and sensitivity analysis.
  • Built a time-series analysis pipeline on IPEX electricity and gas datasets with 15+ statistical tests.
  • Benchmarked 3 pricing methodologies (closed-form, Monte Carlo up to 1M paths, Lewis-Fourier) across 2 stochastic models and 8+ parameter settings, achieving 10⁻¹³ agreement with up to 99.8% runtime reduction for Lewis-Fourier vs Monte Carlo.

Quantitative Research Intern

Jun 2022 — Aug 2022

  • Compared 10+ machine learning models for time-series forecasting on 2 datasets; achieved RMSE 0.0052 and outperformed traditional baselines.
  • Designed a scenario-based forecasting framework linking ML model forecasts to downstream decision systems; evaluated across multiple horizons and parameters, improving performance by about ~3.5% versus baseline approaches.
  • Built Matplotlib/Seaborn analyses and Excel (VBA) monitoring dashboards to track model drift, compare forecasts vs realized values, and summarize backtest performance for decision support.

Education

Polytechnic Engineer, École Polytechnique de Tunisie (EPT)

2020 — 2023

Specialization: Applied Mathematics and Computer Science for Quantitative Finance. Relevant coursework: Stochastic Calculus, Probability and Statistics, Optimization, Numerical Analysis, Linear Algebra, Financial Markets, Algorithms and Data Structures, Databases (SQL), Data Analysis, Machine Learning, Object-oriented Programming.

Preparatory Classes for Engineering Studies, Institut Préparatoire aux Études d'Ingénieur de Sfax (IPEIS)

2018 — 2020

Intensive program in Mathematics and Physics. Ranked 38 out of 1,500 in the national competitive examinations.

Baccalauréat with Honors, Tunisia

2018

Skills

Mathematics & Modeling
Probability, Statistics, Optimization, Stochastic Calculus, Econometrics, Derivatives Pricing, Risk Management, Energy and Financial Markets
Data Science & Analytics
Machine Learning, Deep Learning (LSTM, Transformers, LLM), Reinforcement Learning, Time Series Analysis, Data Visualization & Analysis, Feature Engineering, Backtesting, HPC, Databases (PostgreSQL, SQL Server)
Programming & Software
Python (Polars, PyTorch, TensorFlow, NumPy, Pandas, Scikit-learn), SQL, Git/GitHub, C/C++, AWS Cloud, GCP, MQL5, QuantConnect (Lean)
Languages
English (C1), Italian (B2), French (B2), Arabic (Native)

Activities

Teaching Assistant, Bachelor in Administration and Economics, University of Tor Vergata.

Sep 2024 — Dec 2024

Kaggle Competitor, Ranked 26th of 1,000 teams in the Rohlik Orders Forecasting Challenge: 60-day warehouse order forecasts, scored on MAPE.

Jun 2024 — Aug 2024

Staff Member, 4th Italian Meeting on Probability and Mathematical Statistics, Rome.

Jun 10 — 14, 2024